Global PTC Needle Market Landscape and Competitive Dynamics of Key Manufacturers
Apr 19, 2026
Global PTC Needle Market Landscape and Competitive Dynamics of Key Manufacturers
The market for Percutaneous Transhepatic Cholangiography (PTC) needles-critical instruments in interventional radiology and gastroenterology-exhibits a pattern of moderate concentration. This sector is predominantly steered by a cohort of internationally renowned medical equipment manufacturers who set the pace for innovation and market standards. According to comprehensive industry analyses from 2025, the global PTC needle market is valued at approximately 500million.Projectionsindicatearobustupwardtrajectory,withthemarketanticipatedtoexpandto850 million by 2033, reflecting a healthy Compound Annual Growth Rate (CAGR) of 7%. This sustained growth is underpinned by the rising global prevalence of biliary tract diseases, continuous advancements in minimally invasive surgical techniques, and the accelerating trend of population aging, which collectively amplify the demand for sophisticated diagnostic and interventional tools.
Competitive Landscape and Market Share Distribution
An in-depth examination of market participants reveals a clear hierarchy led by Japanese precision engineering and challenged by the rapid ascent of Asian manufacturing powerhouses.
Hakko Co., Ltd. (Japan): Commanding the leading position with an estimated market share of 26.6%, Hakko is globally revered for its unwavering commitment to precision manufacturing. The company's PTC needles are synonymous with exceptional quality and reliability, supported by a comprehensive product portfolio that spans a wide array of specifications to meet diverse clinical requirements.
Weihai Wego Group (WEGO) (China): Emerging as a formidable contender, WEGO holds a significant market share of approximately 19.7%. The company's growth trajectory is powered by its extensive distribution network across China and the broader Asia-Pacific region, coupled with distinct cost advantages derived from economies of scale. This strategic positioning allows WEGO to penetrate price-sensitive markets effectively while progressively enhancing its global footprint.
GMT Medical and BD (Becton, Dickinson and Company): These established players hold substantial stakes, accounting for about 15.8% and 10.7% of the market, respectively. BD, a global titan in medical technology, leverages its formidable brand equity and deep-seated R&D capabilities to maintain a solid foundation in the PTC needle sector, despite facing intense competition from agile Asian manufacturers.
Other Key Contributors: The competitive mosaic is further enriched by Argon Medical Devices (USA, ~10.3%), ASUKA MEDICAL Inc. (Japan, ~10%), Germany's PAJUNK GmbH, and China's Shanghai Asclepius Medical Technology Co., Ltd. Each of these entities carves out its niche through specialized product offerings and targeted regional strategies.
Strategic Divergence: Innovation vs. Optimization
The competitive strategies employed by these manufacturers reveal a fascinating dichotomy shaped by their geographic origins and corporate philosophies.
The Innovation-Driven Approach (International Giants): Market leaders such as BD and Argon Medical Devices prioritize technological supremacy. Their strategy hinges on aggressive R&D investment aimed at launching next-generation products. Recent innovations focus on enhancing procedural safety through features like hydrophilic coatings-which reduce tissue friction-and radiopaque markers for superior image-guided precision. Ergonomic refinements that improve clinician handling and patient outcomes are also central to their value proposition.
The Value-Optimization Approach (Asian Manufacturers): Conversely, companies like WEGO and Hakko emphasize a balanced strategy that marries high product quality with cost-efficiency. By capitalizing on streamlined manufacturing processes and hyper-responsive regionalized customer service, they offer superior cost-performance ratios. This approach not only makes advanced medical tools more accessible but also challenges the pricing structures of Western counterparts, compelling the entire market toward greater efficiency.
Product Segmentation and Application Analysis
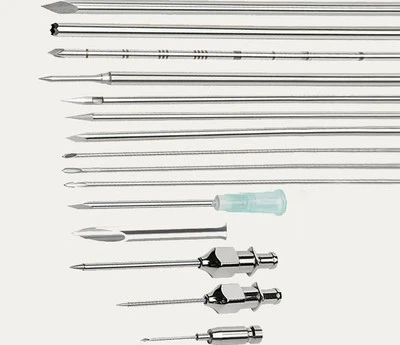
From a product segmentation standpoint, the market is primarily stratified by needle length, with specifications including 150mm, 180mm, and 200mm. The 180mm specification currently dominates the market, striking an optimal equilibrium between operational convenience and versatility across a spectrum of surgical procedures. However, as surgical complexities increase-particularly in accessing deeper or more anatomically challenging lesions-demand for longer variants, notably the 200mm needles, is witnessing a steady uptick.
Regarding application scenarios, the market exhibits a high degree of concentration within hospital settings, which command over 60% of the total market share. This dominance is intrinsically linked to the fact that hospitals serve as the primary venues for high-difficulty diagnostic and interventional treatments, equipped with the necessary infrastructure and specialized personnel that outpatient centers often lack.
Future Outlook and Regional Dynamics
In summation, the PTC needle market is a fiercely competitive arena driven by the synergistic forces of technology, brand equity, and distribution channel mastery. While leading enterprises are actively consolidating their positions through continuous product innovation and strategic partnerships, emerging markets present fertile ground for new entrants. These newcomers can carve out niches by offering differentiated products and tailored services that address unmet local needs. Looking ahead, as healthcare infrastructure in the Asia-Pacific region undergoes rapid modernization and the rates of biliary disease diagnosis improve, the competitive intensity within this region is poised to escalate dramatically. This will likely trigger further market fragmentation and innovation, ultimately benefiting healthcare providers and patients worldwide with more advanced and accessible treatment options.