Global Industry Chain Positioning Of Puncture Needles
Apr 10, 2026
Global Industry Chain Positioning of Puncture Needles: Transformation from "Medical Consumable" to "Precision Medicine Platform Gateway"
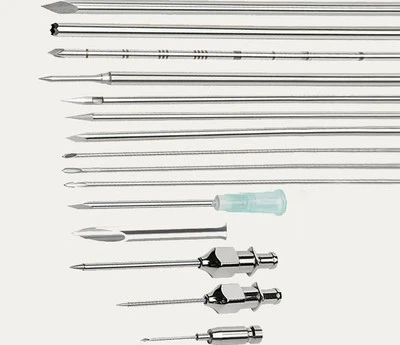
Needle meaning within the global medical device industry value network is undergoing a strategic upgrade from a low-value consumable to a critical component of high-value diagnostic platforms. Its industrial role has evolved from a simple "single-use device" to an ecosystem hub connecting upstream materials science, midstream high-end manufacturing, downstream clinical diagnostics, and data services. This article will analyze the value reconstruction path and future ecological niche of the puncture needle industry chain.
Value Migration Model of the Puncture Needle Industry Chain
The value of the puncture needle industry is migrating along the path of "Consumable → Component → System → Platform." The consumable level focuses on mass production and sales with a gross margin of 15-25%, represented by traditional device OEMs. The component level focuses on customized OEM/ODM with a gross margin of 30-45%, represented by companies like Kindly and Terumo. The system level focuses on solution-based bundled sales with a gross margin of 50-65%, represented by Boston Scientific and Medtronic. The platform level focuses on data services and ecosystem monetization with a gross margin of 70-85%, represented by Intuitive Surgical and Siemens Healthineers. This value migration reflects the transformation of puncture needles from simple commodities to complex components of the medical ecosystem.
Restructuring of the Global Industry Landscape
Competition for technological high ground presents a differentiated competitive landscape: In the field of intelligent puncture navigation, patent density reaches 420 patents per 10billion,withtheUSleadingat5210 billion, with Europe leading at 35%, focusing on rotational cutting mechanical design and sample preservation. Rapid molecular diagnostics has a patent density of 510 per 10billion,withChinarisingto2810 billion, with Japan/South Korea leading at 41%, focusing on controlled degradation and drug sustained release. The global division of manufacturing clusters forms a specialized pattern: The Germany/Switzerland cluster focuses on ultra-high precision grinding and surface treatment, holding 80% of the high-end biopsy needle market share. The US New England cluster leads intelligent puncture system integration, deeply integrated with surgical robot companies. The China Yangtze River Delta/Pearl River Delta cluster mass-produces mid-range products, accounting for 65% of global production capacity, and is extending upstream into materials. The Japan Kansai cluster monopolizes the manufacture of ultra-fine puncture needles, holding 95% of the global market share.
Business Model Evolution in the Puncture Needle Industry
The traditional model focused on standard specification puncture needles, sold through multi-tier distributor networks, using cost-plus pricing with unit prices of 2−20, and transactional customer relationships. The current mainstream model has shifted to product bundles of puncture needle + navigation software + consumable kits, using direct sales + agent channels, adopting a razor-and-blades pricing model, with a value proposition of improving diagnostic efficiency and accuracy. The emerging platform model has developed into intelligent puncture systems + cloud data platforms, charging via subscription models with hospital annual fees of 50,000−200,000, monetizing data through licensing de-identified pathological data to pharmaceutical companies, and expanding the ecosystem by establishing data alliances with gene sequencing companies and drug manufacturers. This evolution reflects the shift in business logic from product sales to service delivery to ecosystem co-creation.
Global Coordination of Industry Standards and Regulations
As a Class II/III medical device, puncture needles face an increasingly complex global regulatory environment. Key market access requirements include: US FDA via 510(k)/De Novo pathways, with core requirements of substantial equivalence/clinical data, an approval cycle of 6-18 months, and a trend towards stricter Software as a Medical Device (SaMD) requirements. EU MDR classified under Rule 8/10, with core requirements of clinical evaluation reports + post-market surveillance, an approval cycle of 12-24 months, and a trend towards higher clinical evidence requirements. China NMPA based on classification catalog, with core requirements of type testing + clinical trials, an approval cycle of 12-24 months, accelerated via innovation channels. Japan PMDA based on the Pharmaceutical Affairs Law, with core requirements of clinical data + GCP inspection, an approval cycle of 18-30 months, linked to insurance pricing. Key international standard systems include ISO 13485 for medical device quality management systems, ISO 23908 for sharps injury protection requirements, ISO 7864 for general requirements for hypodermic needles, ISO 1135-4 for transfusion and infusion equipment, and China's YY/T 0287 for specific requirements.
Strategic Security and Resilience of the Supply Chain
The puncture needle industry chain faces multiple challenges. Regarding raw materials, medical stainless steel prices fluctuate ±40%, and nickel-titanium alloy supply is constrained. The industry responds through strategic reserves, material diversification, and vertical integration. Leading companies like Medtronic sign 5-year long-term agreements with ATI, and Boston Scientific develops cobalt-chromium alloy needles. In precision manufacturing, Swiss/German high-end machine tool lead times extend to 18 months. The industry responds through equipment sharing alliances, domestic substitution, and process innovation. MicroPort collaborates with Shenyang Machine Tool to co-develop specialized grinders. In logistics and inventory, air freight costs increase by 120%, and regional conflicts affect Asia-Europe channels. The industry responds through regionalized production, nearshoring, and digital inventory management. Johnson & Johnson establishes regional centers in Puerto Rico, Ireland, and Singapore. Regarding technical labor, there is a 30% shortage of senior technicians with a 2-3 year training cycle. The industry responds through university-enterprise order-based training programs, automation substitution, and global talent sharing initiatives. Terumo establishes training centers in Japan, China, and Malaysia.
The Data Value Chain of the Puncture Needle Industry
The value of puncture needles as a clinical data entry point is being unleashed. Data collection dimensions include operational data, sample data, and patient data. Data application scenarios encompass clinical decision support, product R&D optimization, medical quality control, and drug R&D support. Data monetization paths are diversified: medical institutions pay annual fees for data platforms and quality control services; pharmaceutical companies purchase de-identified data for target discovery and clinical trial design; insurance companies use puncture quality data for precise underwriting and claims processing; research institutions license data for medical research. This mining of data value transforms the puncture needle from a physical tool into a data node within the digital healthcare ecosystem.
Conclusion
The puncture needle industry is transitioning from a "manufacturing economy" to a "digital economy" and an "ecosystem economy." Leading enterprises are constructing a complete "device-consumable-data-service" ecological closed-loop using the puncture needle as a high-frequency usage gateway. The core of future competition will be data accumulation capability and ecosystem building capability. The standardized, structured clinical data collected by puncture needles will become high-quality fuel for training medical AI. The auxiliary diagnostic algorithms developed based on this data will, in turn, feed back into clinical practice through puncture navigation systems, creating a reinforcing loop. This tiny puncture needle is becoming the strategic fulcrum leveraging a multi-billion-dollar precision medicine data ecosystem.